The Data Center Boom Faces A Reality Check As Infrastructure Constraints Stall AI Ambitions

The meteoric rise of generative artificial intelligence has triggered a massive, global race to construct the physical infrastructure necessary to power the next generation of computing. Data centers—the sprawling, energy-intensive warehouses that host the servers and GPUs fueling AI models—are being announced at an unprecedented clip. However, this gold rush is increasingly hitting a wall of systemic, real-world obstacles that threaten to derail billions of dollars in planned capital expenditures. From acute electricity shortages and grid instability to local regulatory pushback and complex permitting delays, the "AI infrastructure supercycle" is entering a more sober, challenging phase where the distinction between shovel-ready projects and speculative vaporware has become a critical concern for investors and industry stakeholders alike.
The Anatomy of the Infrastructure Bottleneck
At the heart of the current crisis is a fundamental mismatch between the projected power requirements of AI models and the current capacity of the world’s aging electrical grids. Data centers are not merely office buildings; they are industrial-scale power consumers. A single modern hyperscale facility can require hundreds of megawatts of electricity—a load comparable to that of a mid-sized city.
The surge in demand is putting immense pressure on utility companies, which were already struggling to modernize their infrastructure to support the transition to renewable energy. As TechCrunch’s Equity podcast recently explored with guest Brent Nelson, senior managing director of markets and strategy at Ascend Analytics, the industry is currently navigating a period of profound uncertainty. While developers are filing for massive power connections, many of these requests are being met with multi-year wait times or outright rejections by regional transmission organizations (RTOs) tasked with maintaining grid reliability.
A Chronology of the Stalled Boom
The escalation of these challenges has unfolded over the past 24 months, shifting from localized logistical issues to systemic industry-wide hurdles:
- 2023: The Early Warning Signs: As ChatGPT and other large language models gained mass adoption, cloud providers began placing unprecedented demands on energy grids. Early warnings from grid operators like PJM Interconnection highlighted that the sheer speed of the load growth was outpacing the construction of new generation and transmission assets.
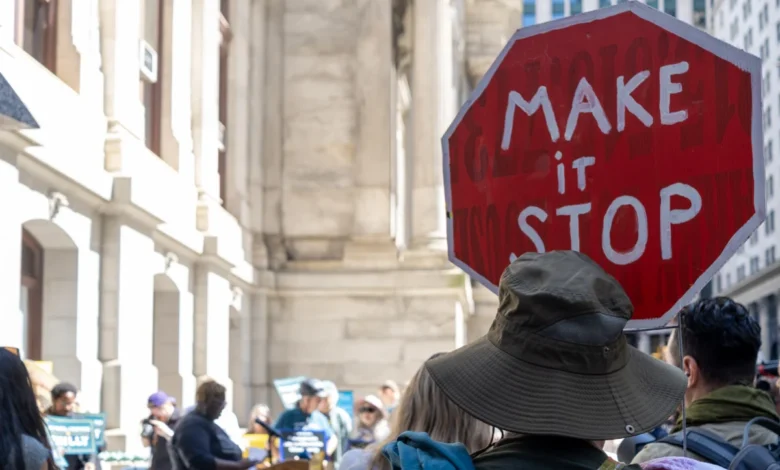
- Early 2024: Regulatory Friction: Local communities, previously eager for the tax revenue promised by data centers, began organizing against the industrialization of their regions. Concerns over noise, water usage for cooling, and visual blight led to the first wave of zoning moratoria.
- Mid-2024: The Power Crunch: The situation reached a boiling point as major utility providers in the U.S. began to signal that they could no longer guarantee power for proposed data center projects without significant upgrades to the grid—upgrades that could take a decade to complete.
- Late 2024 – Present: The Sorting Phase: The industry has moved into a "weeding out" period. Analysts and investors are now scrutinizing project pipelines, looking for signs of genuine commitment, such as signed power purchase agreements (PPAs) and finalized land-use permits, rather than mere speculative site reservations.
The Economic Stakes and Speculation
The financial implications of this slowdown are significant. Estimates suggest that hundreds of billions of dollars are earmarked for data center construction globally through 2030. When a project fails to move forward, it represents not just a lost opportunity for the developer, but a wasted investment in the surrounding infrastructure and a delay in the deployment of AI capabilities that businesses are counting on for future growth.
The danger, according to experts like Nelson, lies in the "placeholder" culture that has emerged in the industry. Because power capacity is a limited resource, some developers have filed for interconnection queues without having the financial backing or technological plans to actually execute. This "queue squatting" clogs the system, preventing viable projects from moving forward and forcing grid operators to waste time evaluating speculative proposals.
Grid Strain and the Energy Trilemma
The difficulty in powering these centers is exacerbated by what energy experts call the "energy trilemma": the need to balance security, affordability, and sustainability. Data centers are under pressure to be "green," yet the demand for 24/7, high-uptime power often forces developers to rely on fossil-fuel-heavy grids.
In Texas, for example, the state’s independent power grid has faced intense scrutiny. Governor Greg Abbott and state regulators have recently called for audits and placed temporary halts on new data center applications. The primary concern is that the sheer volume of new load could lead to price spikes for residential consumers and threaten the stability of the grid during peak weather events. This is not a unique phenomenon; similar tensions are playing out in Virginia, the data center capital of the world, and across major hubs in Northern Europe and Asia.
Institutional Responses and Strategic Shifts
In response to these hurdles, the industry is undergoing a strategic pivot. Major hyperscalers—including Microsoft, Google, and Amazon—are no longer just acting as customers of utilities. They are becoming active participants in the energy market. We are seeing an increase in:
- Direct Energy Investment: Tech giants are investing directly in nuclear power, geothermal energy, and advanced battery storage to ensure they have a reliable, carbon-free energy supply that is independent of the general grid.
- Strategic Site Selection: Developers are moving away from congested urban hubs and toward regions with excess energy capacity, even if it requires significant investment in new transmission lines.
- Efficiency Upgrades: Companies are redoubling their efforts to improve Power Usage Effectiveness (PUE) metrics, utilizing AI to optimize cooling systems and server loads, thereby reducing the total power requirement per unit of compute.
The Road Ahead: Beyond the Hype
The path to a mature AI infrastructure landscape will likely be defined by consolidation. The projects that will succeed are those that have successfully navigated the regulatory maze, secured ironclad power agreements, and engaged with local stakeholders early in the development process.
As investors and policymakers look to the future, the focus is shifting from "how fast can we build?" to "how sustainably can we scale?" The reality is that the physical limits of the electrical grid will continue to act as a governor on the speed of AI deployment. While this may feel like a slowdown to the tech industry, it is a necessary stabilization for the infrastructure sector.
The narrative of the "data center boom" is evolving into a more complex story of grid modernization and energy transition. As TechCrunch’s Equity team continues to track these developments, the central question remains: will the physical world be able to keep pace with the digital demand? The answer, for now, suggests that only the most well-capitalized and strategically sound projects will survive this period of intense scrutiny. The era of speculative expansion is drawing to a close, replaced by a more disciplined, resource-conscious, and engineering-focused approach to the backbone of the artificial intelligence revolution.
For observers of the tech market, the coming years will serve as a definitive test of the industry’s ability to reconcile its high-growth ambitions with the immutable constraints of the physical world. Those who can solve the energy equation will likely define the next decade of computing, while those who cannot will find themselves left behind in the queue.